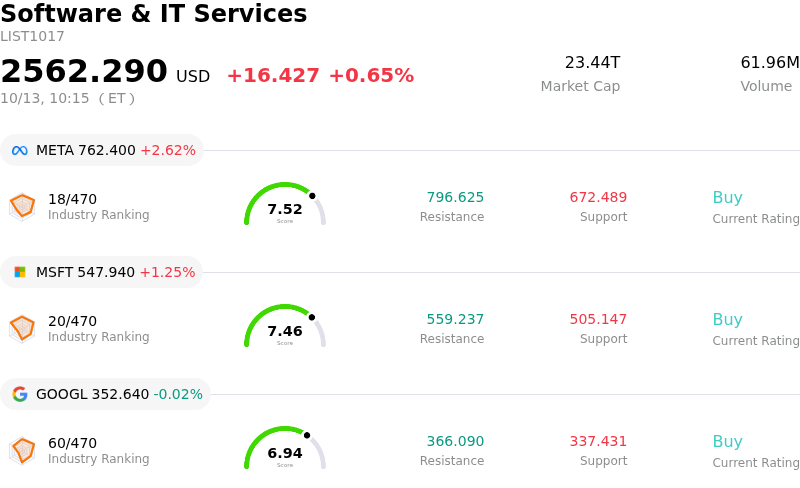
Salesforce Inc (CRM) moved up by 3.49%. The Software & IT Services sector is up by 0.65%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) up 2.56%; Microsoft Corp (MSFT) up 1.25%; Alphabet Inc Class A (GOOGL) up 0.16%.
What is driving Salesforce Inc (CRM)’s stock price up today?
Salesforce experienced a notable upward trajectory driven by a major shift in Wall Street sentiment. A rare double upgrade from Bank of America Securities, which shifted its rating directly from Underperform to Buy while substantially raising its price target, served as a key catalyst. The upgrade directly counters widespread market fears that generative artificial intelligence would cannibalize established enterprise software platforms. Analysts increasingly contend that large enterprise customers are unlikely to replace core operations and mission-critical workflows, positioning Salesforce to integrate autonomous AI agents seamlessly into its existing ecosystem rather than face structural disintermediation.
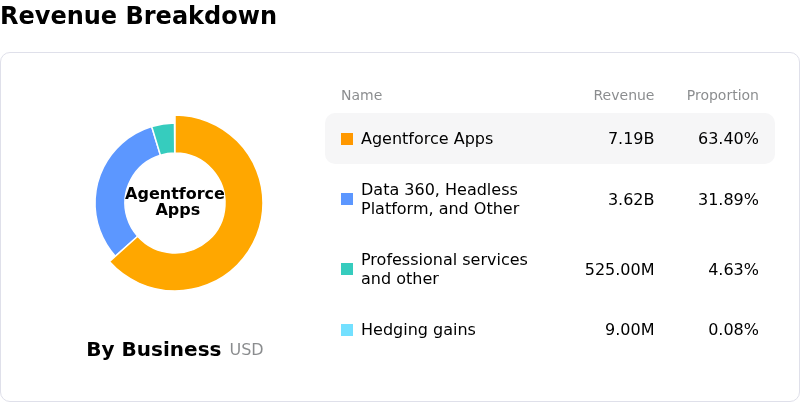
Underpinning this improved analyst outlook is accelerating commercial traction across Salesforce's artificial intelligence portfolio, particularly its Agentforce platform and Data Cloud solutions. Annual recurring revenue tied to Agentforce has demonstrated substantial triple-digit year-over-year growth, offering tangible evidence that the company is successfully executing a transition toward consumption-based AI pricing models. Complementing this organic momentum, strategic tuck-in acquisitions, such as the agreement to acquire AI analytics platform Loops, reinforce Salesforce's ability to deepen customer engagement and expand enterprise analytics capabilities. Robust remaining performance obligations and expanding operating margins further reassure institutional investors of durable underlying execution.
The intraday price action was characterized by heightened volatility as market participants balanced broader macroeconomic uncertainties against company-specific growth drivers. The stock had previously faced sector-wide selling pressure over software disruption concerns, creating an attractive valuation entry point relative to its strong cash flow generation and aggressive share repurchase program. While short-term trading volatility remains elevated amid ongoing debates over enterprise tech budgets, the convergence of strong AI monetization metrics, solid underlying financial execution, and major Wall Street rating upgrades has catalyzed renewed buying interest among institutional portfolios seeking quality enterprise software exposure.
Technical Analysis of Salesforce Inc (CRM)
Technically, Salesforce Inc (CRM) shows a MACD (12,26,9) value of -0.832, indicating a neutral signal. The RSI at 59.195 suggests neutral condition and the Williams %R at 8.317 suggests overbought condition. Please monitor closely.
Media Coverage of Salesforce Inc (CRM)
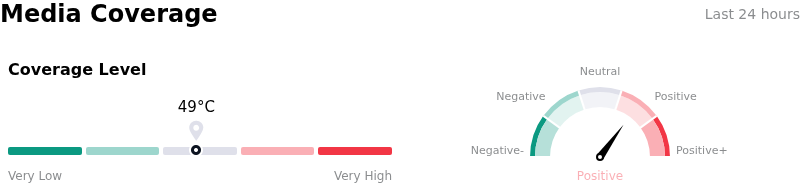
In terms of media coverage, Salesforce Inc (CRM) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Salesforce Inc (CRM)
Salesforce Inc (CRM) is in the Software & IT Services industry. Its latest annual revenue is $41.52B, ranking 13 in the industry. The net profit is $7.46B, ranking 15 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $290.80, a high of $475.00, and a low of $195.00.
More details about Salesforce Inc (CRM)
Company Specific Risks:
- Decelerating Organic Growth Disconnect: Institutional research from Morgan Stanley and KeyBanc highlights a persistent disconnect where rapid Agentforce AI adoption has failed to accelerate organic revenue growth, which remains sluggish at roughly 6% to 7% excluding recent acquisitions.
- Disruption to Per-Seat SaaS Pricing: The industry-wide transition toward autonomous AI agents risks cannibalizing Salesforce's core subscription model, as automated agent workflows threaten to diminish traditional per-user seat counts across enterprise clients.
- Balance Sheet Leverage and Rating Pressure: Debt-to-equity reaching elevated levels above 110%—compounded by heavy cash outlays for acquisitions like Informatica and a massive $50 billion buyback program—has triggered credit agency warnings over deteriorating debt-to-EBITDA metrics.
- Monetization Friction for High-Tier AI Offerings: Pushing customers toward premium pricing tiers such as the $550 per-user monthly AIforce Max suite faces resistance, as cautious corporate IT spending and elongated enterprise sales cycles delay meaningful monetization.
Find out more